The Green Sheet Online Edition
September 14, 2026 • 26:09:01
Jevon's Paradox and payments
Most artificial intelligence discussions in payments center on cost reduction and job displacement. Economics, however, suggests the opposite may occur. Jevons' Paradox tells us when technology makes a task more efficient, total consumption of that task actually increases as lower costs make it more accessible and expands demand.
English economist William Stanley Jevons observed this with coal in Britain: more efficient steam engines lowered the cost of using coal, which ultimately increased total coal consumption because many new applications became economically viable. But will Jevons' Paradox hold in payments?
AI luminary, Geoffrey Hinton famously predicted in 2016 that AI would soon perform essentially all of the work of radiologists. Although AI has become remarkably capable at image analysis, the broader prediction has not materialized. The number of practicing U.S. radiologists has remained relatively stable while physician compensation has increased substantially.
AI has generally increased productivity and expanded the demand for imaging services. Rather than replace professionals, AI has enabled them to do more work and to deliver higher-value services, which I expect to be replicated in payments.
AI in underwriting
Extrapolating Jevons' Paradox and Hinton's prediction to payments tells us AI is unlikely to reduce the need for experienced underwriting and risk professionals. Instead, it is more likely to shift their work toward higher-value judgment while expanding the overall amount of underwriting and merchant monitoring performed.
By making more comprehensive underwriting economically practical, AI has the potential to increase revenue opportunities and raise demand for experienced risk professionals. As with every technological shift, however, there will be winners and losers depending on who adopts these capabilities most effectively.
Payments underwriting shares many characteristics with radiology. Both disciplines involve reviewing large amounts of information, identifying patterns, and exercising professional judgment under uncertainty.
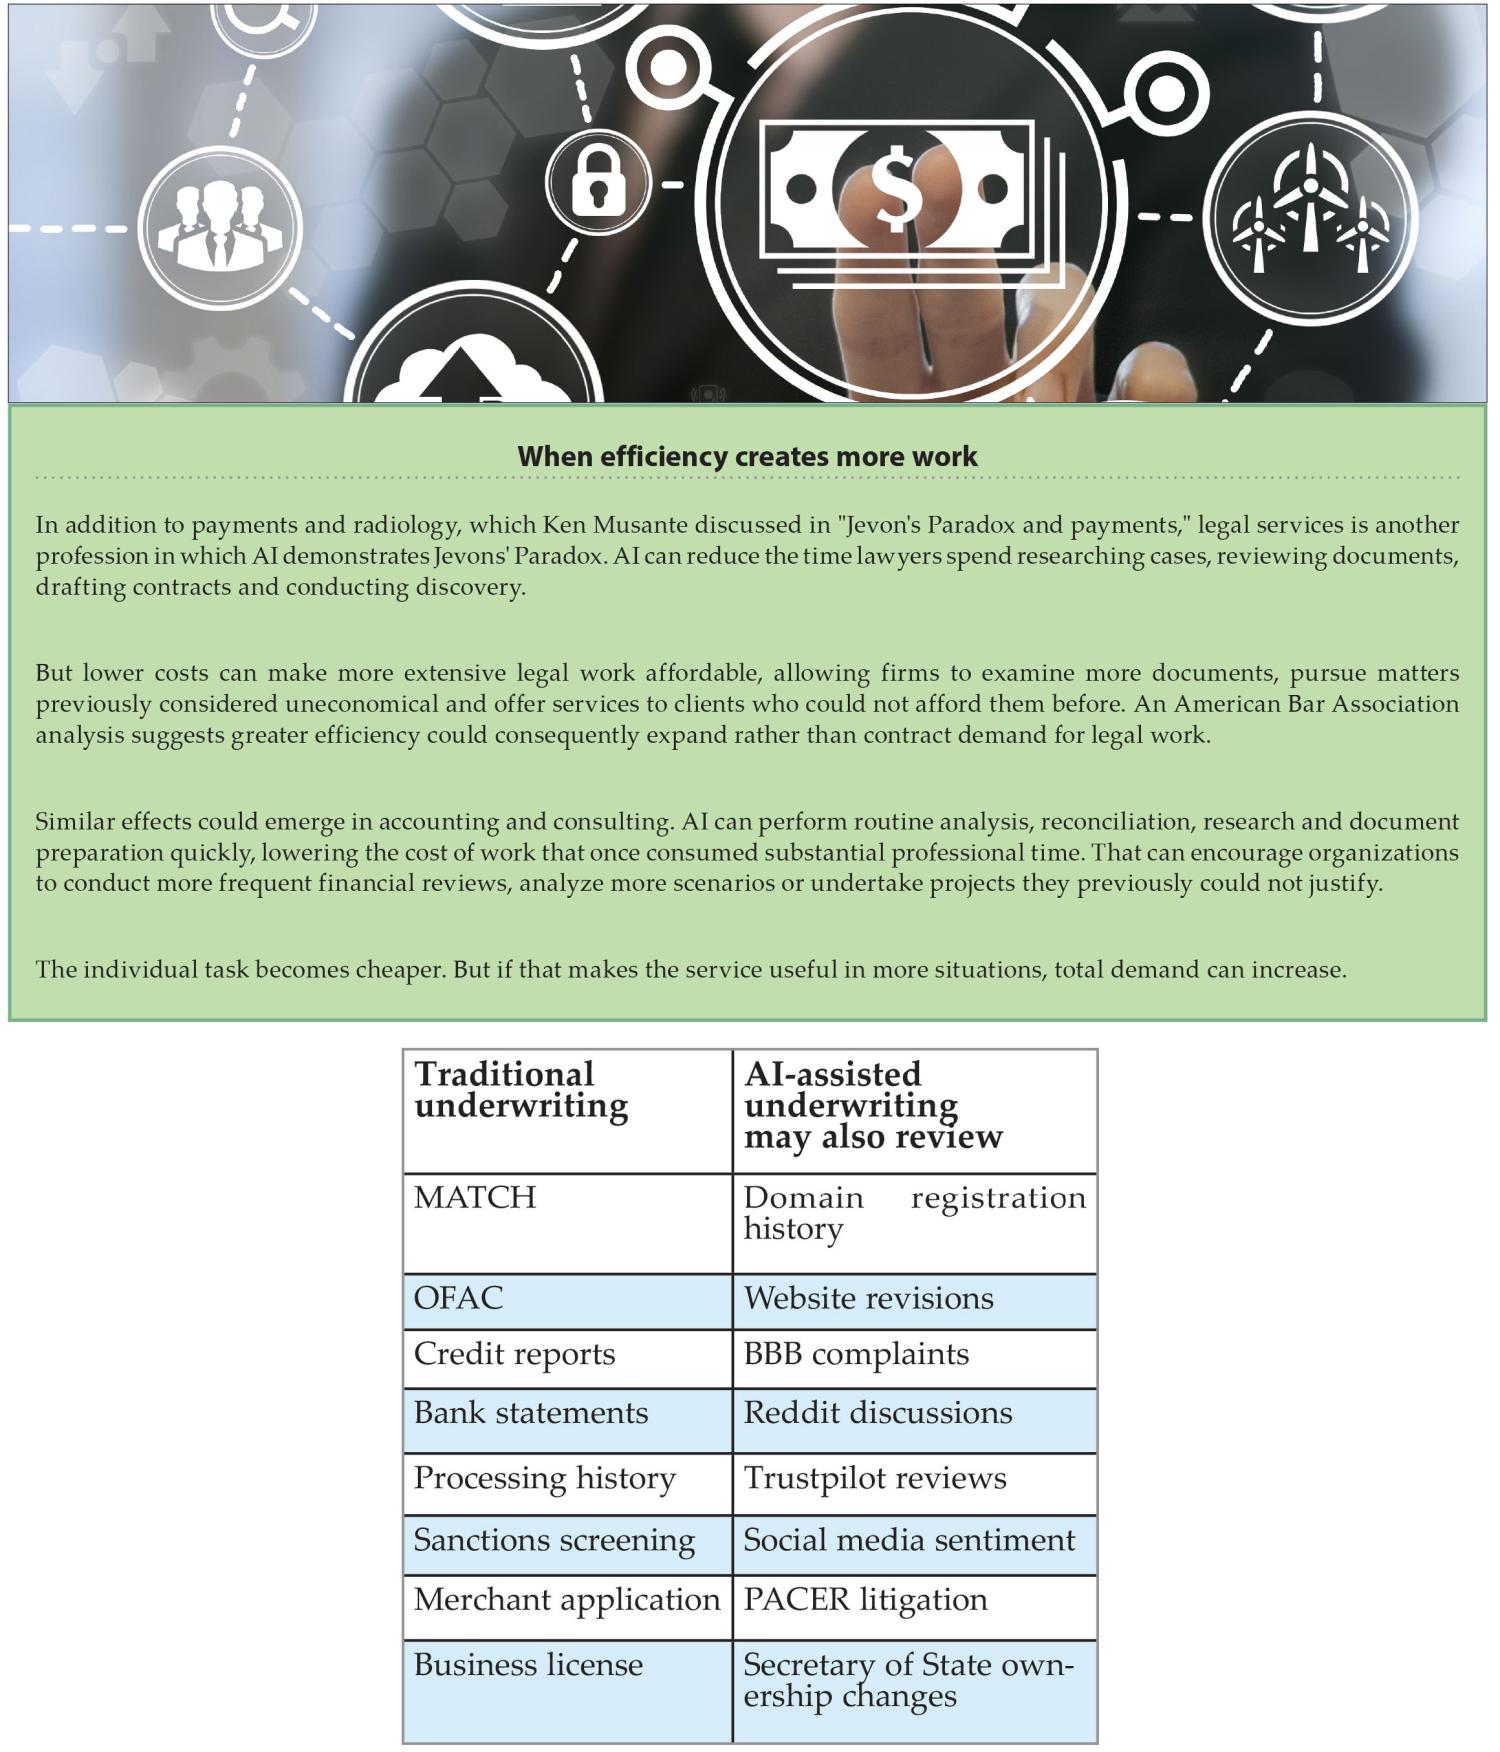
Manually reviewing merchant files increases approval times. A manual review may require an underwriter to examine business formation records, principal and beneficial owner information, credit reports, bank statements, processing history, MATCH results, sanctions screenings, websites, refund and cancellation policies, product offerings, fulfillment practices, litigation records, consumer complaints, and other third-party data.
Because considerably more information is available today, reviewing and reconciling each source individually can be time-consuming. The cost disparity may also be significant, as human labor generally costs more than the computing resources or tokens required to perform an automated review.
Historically, underwriting was constrained by the cost of obtaining and reviewing information. Every additional database, document, website, or litigation search required additional human effort.
AI changes that equation. When the marginal cost of evaluating another source is low, organizations naturally consume more information because the additional insight exceeds the incremental cost. In this sense, automation does not merely replace existing underwriting work; it expands the scope, depth and frequency of underwriting.
Consistent with Jevons' Paradox, automation may make traditional underwriting faster and less expensive on a per-file basis, but those efficiency gains are unlikely to reduce the overall amount of underwriting performed.
(See attached table)
AI also changes the economics of continuous underwriting. Rather than reviewing merchants only during onboarding or after a significant event, payment providers can economically justify evaluating every merchant every day. This transforms underwriting from a point-in-time decision into a continuous risk management process.
AI in merchant monitoring
Merchant monitoring provides an even clearer illustration of Jevons' Paradox. The greatest increase in monitoring may not occur in high-risk merchants, but among low-risk merchants that historically received little attention because the economics did not justify frequent review. Continuous AI monitoring makes ongoing surveillance economically feasible across an entire merchant portfolio.
Automation enables monitoring systems to review substantially more information, at greater frequency, and with far greater depth than is practical through manual processes alone. Instead of relying on periodic reviews or a limited set of predefined alerts, automated systems can continuously evaluate numerous internal and external data sources. Because the incremental cost of evaluating additional data is relatively low, automated monitoring naturally expands the number and sophistication of risk indicators or "signals" that may be considered.
And, every piece of information that may improve a prediction is commonly referred to as a signal. AI dramatically lowers the cost of collecting and evaluating these signals. Consequently, payment providers are likely to consume more signals, not fewer, in much the same way that lower computing costs led society to consume dramatically more computing power.
Financial institutions and payment processors are incentivized to review a broader universe of merchants, evaluate a greater number of risk factors, perform more frequent reassessments, and investigate emerging risks that would have been prohibitively time-consuming or expensive in a manual environment.
Automation, however, will not replace experienced risk professionals. Automated systems excel at identifying anomalies, correlating large volumes of information and prioritizing potential issues, but they generally lack the contextual judgment necessary to evaluate nuanced business circumstances, distinguish meaningful risks from false positives, or balance regulatory and commercial considerations.
The debate surrounding AI often assumes that greater efficiency necessarily means fewer jobs and less work. Jevons' Paradox suggests precisely the opposite. In payments, AI is likely to increase the demand for underwriting, merchant monitoring and professional judgment. The winners will be those who combine AI's ability to process enormous amounts of information with the experience required to interpret it. 
As founder of Humboldt Merchant Services, co-founder of Eureka Payments, and a former executive for such payments innovators as WePay, a division of JPMorgan Chase, Ken Musante has experience in all aspects of successful ISO building. He currently provides consulting services and expert witness testimony as founder of Napa Payments and Consulting, www.napapaymentsandconsulting.com. Contact him at kenm@napapaymentsandconsulting.com, 707-601-7656 or www.linkedin.com/in/ken-musante-us.
Notice to readers: These are archived articles. Contact information, links and other details may be out of date. We regret any inconvenience.